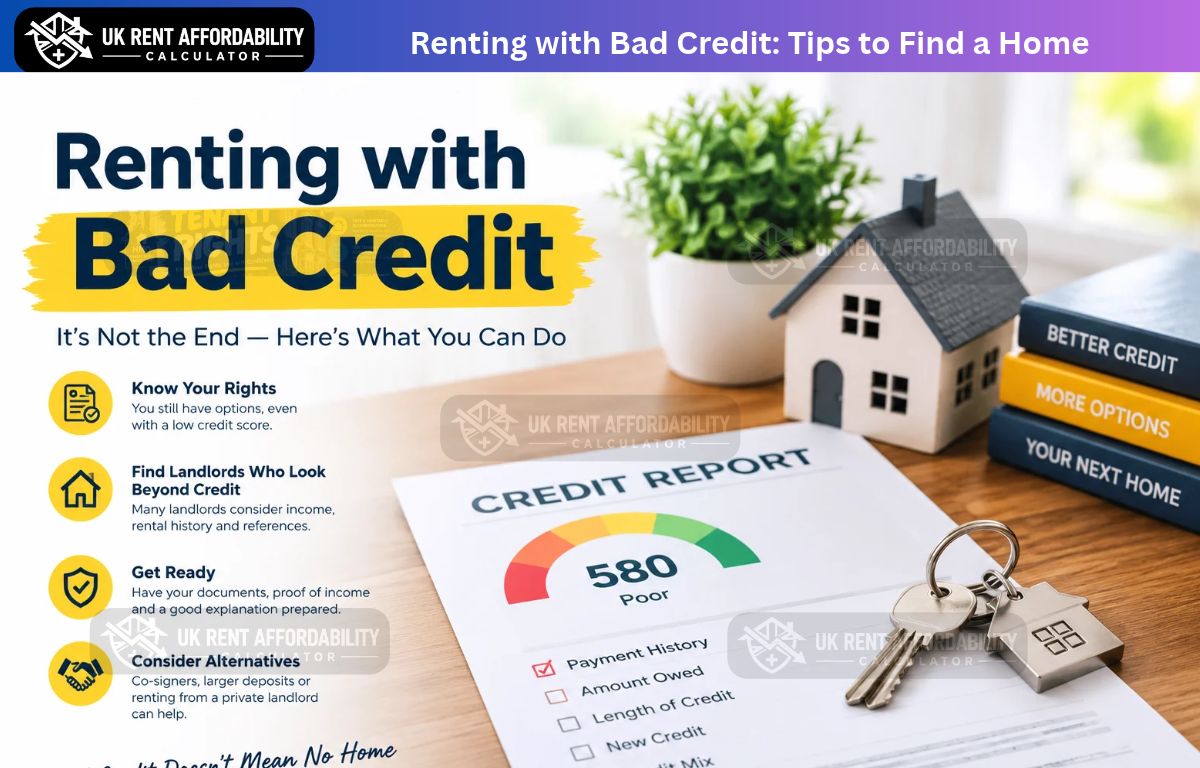
Jemima is 29, works full-time as a care assistant in Leeds, and has never missed a rent payment in four years. Yet every letting agent she applies to comes back with the same answer: no. The reason sits on her credit file — a county court judgment for £620 from an old energy bill she thought had been sorted, plus two missed mobile phone payments from 2024. Her income covers the rent, and her last landlord would give her a glowing reference. But the credit check keeps closing doors before anyone looks at the rest. Renting with Bad Credit can be challenging, even when you have a reliable income and a strong rental history.
If that sounds familiar, this guide is for you. Bad credit does not mean you cannot rent in the UK. It means understanding exactly what landlords and agents see, how long each mark on your file lasts, and which practical steps actually get applications accepted.
Quick Answer: Yes, you can rent with bad credit in the UK — there is no law that stops a landlord letting to you because of your credit history, and there is no universal credit score you must pass. What matters is what shows on your file (CCJs, defaults, IVAs and bankruptcy stay for six years), whether your income passes the usual 30-times-monthly-rent test, and whether you can offer a guarantor, a strong reference or an evidence pack. Since 1 May 2026 a landlord can ask for at most one month’s rent in advance, so offering several months upfront is no longer an option.
Can You Rent a House with Bad Credit in the UK?
Yes. No law in England bans landlords from letting to someone with Renting with Bad Credit, and no minimum credit score exists in legislation. A landlord or agent can set their own criteria, and many use credit checks in referencing — but a poor credit history is a risk factor they weigh, not a legal bar.
That distinction matters: your application is never decided by a single number. Agents weigh your income, employment, previous landlord’s reference, and what is on your file — a satisfied CCJ from three years ago looks very different from an unpaid one from three months ago.
High-street letting agents with strict referencing policies are the hardest route. Private landlords, smaller agencies and landlords who manage their own properties have far more discretion, and many will listen to an explanation and look at your evidence. Your job is to get in front of the decision-maker with the strongest application you can put together — and this guide shows you how.
What Landlords and Agents Actually See on a Credit Check
Tenant referencing usually involves a soft credit check, which does not affect your score. It flags the risks a landlord cares about: unpaid debts that went to court, formal insolvency, and a pattern of missed payments.
| What appears | What it tells the landlord |
|---|---|
| County Court Judgment (CCJ) | A court ordered you to pay a debt — the biggest red flag |
| Default | A lender closed an account because payments stopped |
| Individual Voluntary Arrangement (IVA) | A formal agreement to repay debts over several years |
| Bankruptcy | A court declared you unable to pay your debts |
| Missed or late payments | Individual payments made late — a pattern matters most |
| Electoral roll entry | Confirms identity and address |
What does not usually appear is just as important. Your salary is not on your credit file — the agent checks that separately through payslips or an employer’s reference. Your rent payment history is not on your file either, unless it is being reported through a scheme such as the Experian Rental Exchange. And your credit file does not show why a debt arose: a CCJ for a bill you disputed looks identical to one for a debt you ignored — which is why your explanation matters so much.
For the full mechanics of how referencing works, see our guide to tenant referencing in the UK.
There Is No Universal Pass or Fail Credit Score
There is no single credit score and no pass mark you must reach. The UK has three main credit reference agencies, each holding its own version of your credit history and calculating its own score on its own scale.
| Credit reference agency | Score range |
|---|---|
| Experian | 0 to 999 (881 to 960 is rated “good”) |
| Equifax | 0 to 1,000 |
| TransUnion | 0 to 710 |
The score you see on an app is an educational guide. When a landlord or lender assesses you, they look at the underlying data on your report and apply their own criteria. There is no published threshold that guarantees acceptance or rejection, and referencing companies do not all use the same agency — so your file can look different depending on who checks it.
Do not waste energy chasing a particular number. Check your statutory credit report with all three agencies (it is free), look for errors, and focus on what changes how a landlord sees you — your income, your guarantor, your references and your explanation.
CCJs: What They Are and How Long They Last
A County Court Judgment (CCJ) is the single most damaging thing on a tenant’s credit file: a creditor took you to court over an unpaid debt, and the court ordered you to pay. CCJs most often come from unpaid council tax, energy bills, credit cards, loans and phone contracts — and many people first discover one when a referencing check flags it, because the claim went to an old address.
- A CCJ stays on your credit file for six years from the date of the judgment, even if you pay it in full during that time. After six years, it is removed automatically.
- If you pay the full amount within one calendar month of the judgment, the CCJ is removed from the public register and your credit file entirely — as if it never happened. This is the only way to erase a CCJ.
- If you pay after that first month, the CCJ is marked as “satisfied” on your file. It still shows for the full six years, but a satisfied marker looks considerably better to a landlord than an unpaid one.
- The CCJ also appears on the public Register of Judgments, Orders and Fines (Registry Trust) for the same six years.
Important: If you find a CCJ you did not know about, act immediately. Check the court name and case number on your credit report, contact the court for details, and get free advice from National Debtline or Citizens Advice.
For a landlord, an unpaid CCJ suggests you may not pay the rent; a satisfied CCJ with a clean record since suggests a problem that was dealt with. Always tell the agent about a CCJ before they find it.
Defaults and Missed Payments
A default is registered by a lender — a bank, a phone company, a catalogue — when you stop paying an account and do not bring it up to date after being warned. The lender must first send a default notice giving you at least 14 days to catch up; pay within that window and no default is recorded.
- A default stays on your credit file for six years from the date it was registered, whether or not you later pay the debt. Paying it marks it as satisfied, which helps, but does not remove it early.
- Missed and late payments also stay on your file for six years — one late payment is a small mark; a pattern is what worries a referencing company.
- A default is not a court order. It does not carry the same weight as a CCJ, but several defaults together paint a similar picture.
- Settled defaults look better than unsettled ones — if you can afford to settle one, do it, and keep proof to show an agent.
If your file shows defaults rather than a CCJ, your position is stronger than you may think. Many private landlords will accept a tenant with an old, settled default if your income is solid and your previous landlord’s reference is good. Say so upfront and show the settlement.
IVAs, Bankruptcy and Debt Relief Orders
Formal debt solutions leave the deepest marks on a credit file, but they have fixed end dates — and landlords understand that a completed arrangement differs from an ongoing crisis.
| Debt solution | How long it lasts | How long it shows on your file |
|---|---|---|
| Individual Voluntary Arrangement (IVA) | Typically 5 years, sometimes extended to 6 | 6 years from the date the IVA started |
| Bankruptcy | Usually discharged after 12 months; income payments can run for up to 3 years | 6 years from the date of the bankruptcy order |
| Debt Relief Order (DRO) | 12-month moratorium, then qualifying debts are written off | 6 years from the date the DRO was approved |
A DRO is available if you owe £50,000 or less, have no more than £75 a month of spare income, and hold assets worth no more than £2,000 (excluding a vehicle worth less than £4,000). There is no application fee — the £90 fee was abolished in April 2024 — and you apply through an approved debt adviser.
Two points matter for renters. First, an IVA is usually finished within five years but stays on your file for six years from its start date — so the entry may clear only about a year after you complete it. Second, bankruptcy is not a life sentence for renting: you are usually discharged after 12 months, and a discharged bankrupt with a steady income and a guarantor can and does rent. Be upfront about it and show your discharge papers.
How Long Bad Credit Stays on Your File
The six-year rule runs through almost every negative marker: CCJs, defaults, missed payments, IVAs, bankruptcies and Debt Relief Orders all stay on your file for six years from the date they started. Once you know the dates, you can work out exactly when your file clears — and plan your applications around it.
Worked example — Octavia’s CCJ: Octavia, 34, had a CCJ for £480 over an unpaid credit card bill, with the judgment dated March 2023. She paid in full in May 2023 — after the one-month window — so it was marked “satisfied” but stayed on her file. Six years from March 2023 means it drops off in March 2029. Had she paid within one month of the judgment, by April 2023, it would have been removed entirely. On a new CCJ, paying within the first month is the single most valuable thing you can do; on an old one, the satisfied marker plus a clean record since is your best evidence.
Write down the date each marker clears. If your worst mark clears in months, it may be worth waiting; if it clears in years, focus on the routes that work now — a guarantor, a private landlord and a strong evidence pack.
The Affordability Test: The 30x Rule
For many renters with bad credit, the credit check is not the problem — the affordability test is. Most agents use a standard income test: your gross annual income should be at least 30 times the monthly rent (2.5 times the annual rent). It is an industry convention, not a law, but it is applied widely, and failing it is the most common reason applications are refused.
| Monthly rent | Income needed at 30x (tenant) | Guarantor income needed at 36x |
|---|---|---|
| £700 | £21,000 a year | £25,200 a year |
| £850 | £25,500 a year | £30,600 a year |
| £950 | £28,500 a year | £34,200 a year |
| £1,100 | £33,000 a year | £39,600 a year |
| £1,250 | £37,500 a year | £45,000 a year |
| £1,500 | £45,000 a year | £54,000 a year |
Worked example — Rufus’s application: Rufus, 41, earns £30,000 a year and wants a one-bedroom flat at £950 a month. The test needs £950 × 30 = £28,500 a year — so on income alone, he passes. His deposit is capped at five weeks’ rent: annual rent £950 × 12 = £11,400, one week £11,400 ÷ 52 = £219.23, five weeks £1,096.15. His total move-in cost is the first month (£950) plus the deposit — £2,046.15. On £25,000 he would have failed the test despite being able to afford the rent — the point at which a guarantor or joint tenancy becomes essential. See our guide to tenancy deposit protection for the deposit rules in full.
Some agents count the housing element of Universal Credit as income, and some accept savings in place of part of the income — ask before you apply. If you receive Universal Credit, see our guide to how much rent Universal Credit will pay.
Your Guarantor: The Strongest Route to Getting Accepted
If one step turns a refused application into an accepted one, it is a guarantor: someone — usually a parent or close relative — who agrees in writing to pay your rent if you cannot. For a landlord worried about bad credit, a guarantor with a clean file and solid income removes most of the risk.
- The guarantor must be based in the UK, and most agents prefer a homeowner, though this is not a legal requirement.
- The guarantor must pass their own credit and affordability checks. The standard test is stricter than the tenant’s: a guarantor is typically expected to earn at least 36 times the monthly rent a year — three times the annual rent.
- The guarantor is liable for the rent and sometimes for damage too — they should read the agreement carefully before signing.
Worked example — Hector as guarantor: Hector, 58, guarantees his daughter’s tenancy on a flat at £1,100 a month. The guarantor test needs £1,100 × 36 = £39,600 a year; Hector earns £42,000, so he passes. His daughter needs £1,100 × 30 = £33,000 as the tenant but earns £29,000 — so she falls short on her own, and the application is accepted only because of Hector.
If no family member can act as guarantor, a commercial guarantor service — a company that guarantees your rent for a fee, usually around one week’s rent — is another option; some agents accept these and some do not. Our guide to guarantors for renting covers the alternatives in full.
The Evidence Pack That Gets You Past Referencing
Agents decide on paper. If your credit file is the only paper they see, a bad file decides the outcome. An evidence pack puts your strengths in front of them first — prepare it before you start viewing, and send it with every application.
| Document | Why it helps |
|---|---|
| Last 3 months’ payslips | Proves stable, regular income |
| Last 3 months’ bank statements | Shows rent-sized payments leaving on time |
| Previous landlord’s reference | Proves you paid rent and looked after a home |
| Employer’s reference | Confirms your job, salary, and length of service |
| Proof a CCJ or default is satisfied | Turns a red flag into a resolved problem |
| A short written explanation | Explains what happened, in your words |
Your written explanation deserves care. Keep it to a short paragraph: what happened, when, what you did about it, and what has changed since. “In 2023 I had a CCJ for £540 after a phone company continued billing me at an old address. I paid it in full in June 2023 and it is marked satisfied. I have paid my rent on time every month since, as my landlord’s reference confirms.” That beats a page of excuses — and beats saying nothing and letting the referencing report speak for you.
Private Landlords vs Letting Agents
Where you apply matters as much as how you apply. A high-street agent usually has no choice: their referencing provider returns a fail, and their policy says no. A private landlord can look at your evidence pack, meet you, and make their own judgement — that discretion is the single biggest advantage a renter with bad credit has.
| Route | How flexible on bad credit |
|---|---|
| High-street letting agent | Low — strict referencing policies |
| Small independent agent | Medium — some discretion |
| Private landlord | High — their own decision |
Private landlords are most often found on OpenRent, SpareRoom, Gumtree and local Facebook groups — and through word of mouth. When you contact one, lead with your strengths: your income, your reference, your guarantor. Do not open with your credit history, but do not hide it either — explain briefly once they have seen you are a serious applicant, show your evidence, and let them decide with the full picture. Our guide to private landlords vs letting agents explains the trade-offs.
What You Can (and Cannot) Offer to Strengthen Your Application
For years, the standard advice to renters with bad credit was to offer several months’ rent upfront. That advice is now wrong: since 1 May 2026, the rules on rent in advance have changed completely.
| Before 1 May 2026 | From 1 May 2026 |
|---|---|
| Landlords could ask for several months’ rent upfront | No rent can be taken before the tenancy agreement is signed |
| Six months upfront was a common workaround | At most one month’s rent can be paid in advance, after signing |
That change removes one of the old routes, but others remain open. A guarantor is still the strongest option, and explicitly still allowed. A larger deposit is not an option — the deposit is capped at five weeks’ rent where the annual rent is under £50,000 (six weeks at £50,000 or more). A joint tenancy can help if you apply with someone whose income and credit are stronger, though both tenants are jointly liable for the rent.
Do not pay a landlord under the table or hand over cash to get around the rent-in-advance cap. It is not lawful, it leaves you with no proof of payment, and it is a hallmark of the rental scams that target desperate renters. If a landlord asks for more than one month upfront, walk away — and consider reporting them to your local council’s trading standards team.
Fixing Errors on Your Credit File
Before you blame your history, check that your file is accurate — errors are common, and an error can look exactly like bad credit.
- Get your free statutory credit report from Experian, Equifax and TransUnion. You are entitled to it by law, and checking your own file never affects your score.
- Read every entry, not just the score — look for accounts you do not recognise, wrong balances, and markers that should have dropped off after six years.
- Raise a dispute with the agency if anything is wrong — they must investigate, and if the lender cannot prove the entry, it must be corrected or removed.
- Register to vote at your current address. Being on the electoral roll helps agencies confirm your identity and address.
- Add a short explanatory note to your file if there is a marker you cannot remove — lenders must read it when they assess you.
Check your file at least a month before you start applying — disputes can take several weeks to resolve.
Rebuilding Your Credit While You Rent
Getting accepted is the first step; the second is making the next application easier. Rent itself does not normally build your credit score — unlike a mortgage, rent payments are not automatically reported. But there are ways to make your rent count.
- Ask your landlord to report your rent through the Experian Rental Exchange. It is free for both sides, and on-time payments are added to your Experian report and included in your score. Late payments are recorded too — only do this if you pay on time every month.
- Pay every bill on time. Direct debits for phone, energy and council tax remove the risk of a missed payment marking your file.
- Keep your credit use low. If you have a credit card, keep the balance well below the limit and pay more than the minimum each month.
- Do not apply for credit you do not need. Each application leaves a search on your file, and several in a short period can lower your score.
Paying rent on time is also evidence for your next application: keep your bank statements showing the rent leaving each month, and ask your landlord for a written reference when you move on. For more, see our guide to whether paying rent builds your credit score.
If You Are Turned Down: What to Do Next
A refusal is not the end of the process. Ask the agent, in writing, why the application was refused and which referencing company was used — the answer tells you what to fix.
Then work through your options in this order:
- Fix anything wrong on your file, as described above, and reapply once it is corrected.
- Apply with a guarantor — this alone reverses many refusals.
- Target private landlords rather than high-street agents, and lead with your evidence pack.
- Consider a cheaper property where your income passes the 30x test comfortably.
- Apply jointly with someone whose income and credit strengthen the application.
- Ask about a zero-deposit option — some landlords accept deposit replacement insurance instead of a cash deposit. See our guide to zero-deposit renting.
If you are refused because you receive benefits, that is a different matter. Since 1 May 2026 it has been unlawful for a landlord or agent to refuse you, withhold information or prevent a viewing because you have children or receive benefits — though income and affordability can still be considered. Our guide to the No DSS ban explains your rights.
Frequently Asked Questions
Can I rent with bad credit in the UK?
Yes. There is no law that stops a landlord letting to you because of bad credit, and no minimum credit score you must reach. Many landlords will accept you if your income is sufficient, a guarantor is available, or your evidence — references, payslips, proof old debts are settled — is strong.
Can I rent a flat with a CCJ?
Yes, but it is harder. A CCJ stays on your file for six years and is the most serious marker a landlord can see. Your chances are much better if it is marked satisfied, is several years old, and you can show a clean record since — plus a guarantor and a good reference. If it is less than a month old, pay it in full immediately: within one calendar month it can be removed entirely.
Can I rent with bad credit and no guarantor?
Yes, but your options narrow. Focus on private landlords rather than agents, prepare a strong evidence pack, and consider a cheaper property where your income passes the 30x affordability test easily. A joint tenancy with a stronger co-tenant is another route.
What credit score do I need to rent in the UK?
There is no set score. The UK has three credit reference agencies — Experian (0 to 999), Equifax (0 to 1,000) and TransUnion (0 to 710) — each with its own scale, and landlords apply their own criteria to the underlying data. What matters is what is on your file and whether your income and guarantor satisfy the landlord.
How long does a CCJ stay on my credit file?
Six years from the date of the judgment. If you pay in full within one calendar month, it is removed from the register and your file entirely. If you pay later, it is marked as satisfied but stays visible for the full six years.
Can a landlord refuse me because of my credit history?
Yes — a landlord can choose not to let to you because of your credit history. What a landlord cannot do is refuse you because you have children or receive benefits, which has been unlawful since 1 May 2026 under the Renters’ Rights Act 2025.
Will paying rent improve my credit score?
Only if your rent is reported. Rent payments are not automatically added to your credit file. If your landlord reports your rent through the Experian Rental Exchange, on-time payments are added to your Experian report and can help your score. Late payments are recorded too.
What is the 30x rent rule?
It is the standard affordability test used by most letting agents: your gross annual income should be at least 30 times the monthly rent. For a £1,000-a-month flat, that means £30,000 a year. It is an industry convention, not a law. A guarantor is usually expected to earn 36 times the monthly rent.
Can I offer six months’ rent upfront to get accepted with bad credit?
No — not anymore. Since 1 May 2026, a landlord cannot take any rent before the tenancy agreement is signed, and can ask for at most one month’s rent in advance after signing. Use a guarantor, an evidence pack and a private landlord instead.
I have an IVA — can I still rent?
Yes. An IVA stays on your credit file for six years from the date it started, and it typically runs for five years. Many landlords will accept a tenant in or after an IVA if the payments are up to date, the income passes the affordability test, and a guarantor is available.
Final Thoughts
Bad credit makes renting harder, but it does not make it impossible. The renters who get accepted are not the ones with perfect files — they are the ones who understand what the check actually looks at, deal with what they can fix, and present the rest honestly and with evidence. Check your file with all three agencies, pay any recent CCJ within its first month if you possibly can, get a guarantor if one is available, and build your evidence pack before you start viewing. Aim your applications where they have the best chance — at private landlords who can make their own judgement, not only at agents whose systems say no by default.
Before you apply, use our free rent affordability calculator to check what rent your income supports, and read our guide to how to find a rental property in the UK. The fastest wins are the simplest: a satisfied marker, a guarantor, and a landlord who has seen your references before your credit report.
Further Reading
- GOV.UK — Tenant Fees Act 2019: guidance for tenants
- Citizens Advice — Renting privately
- Shelter England — Private renting advice